Global Potato Prices, Week 41/2026: Record 17x Gap, a New World Floor in Pakistan, and France at an All-Time High
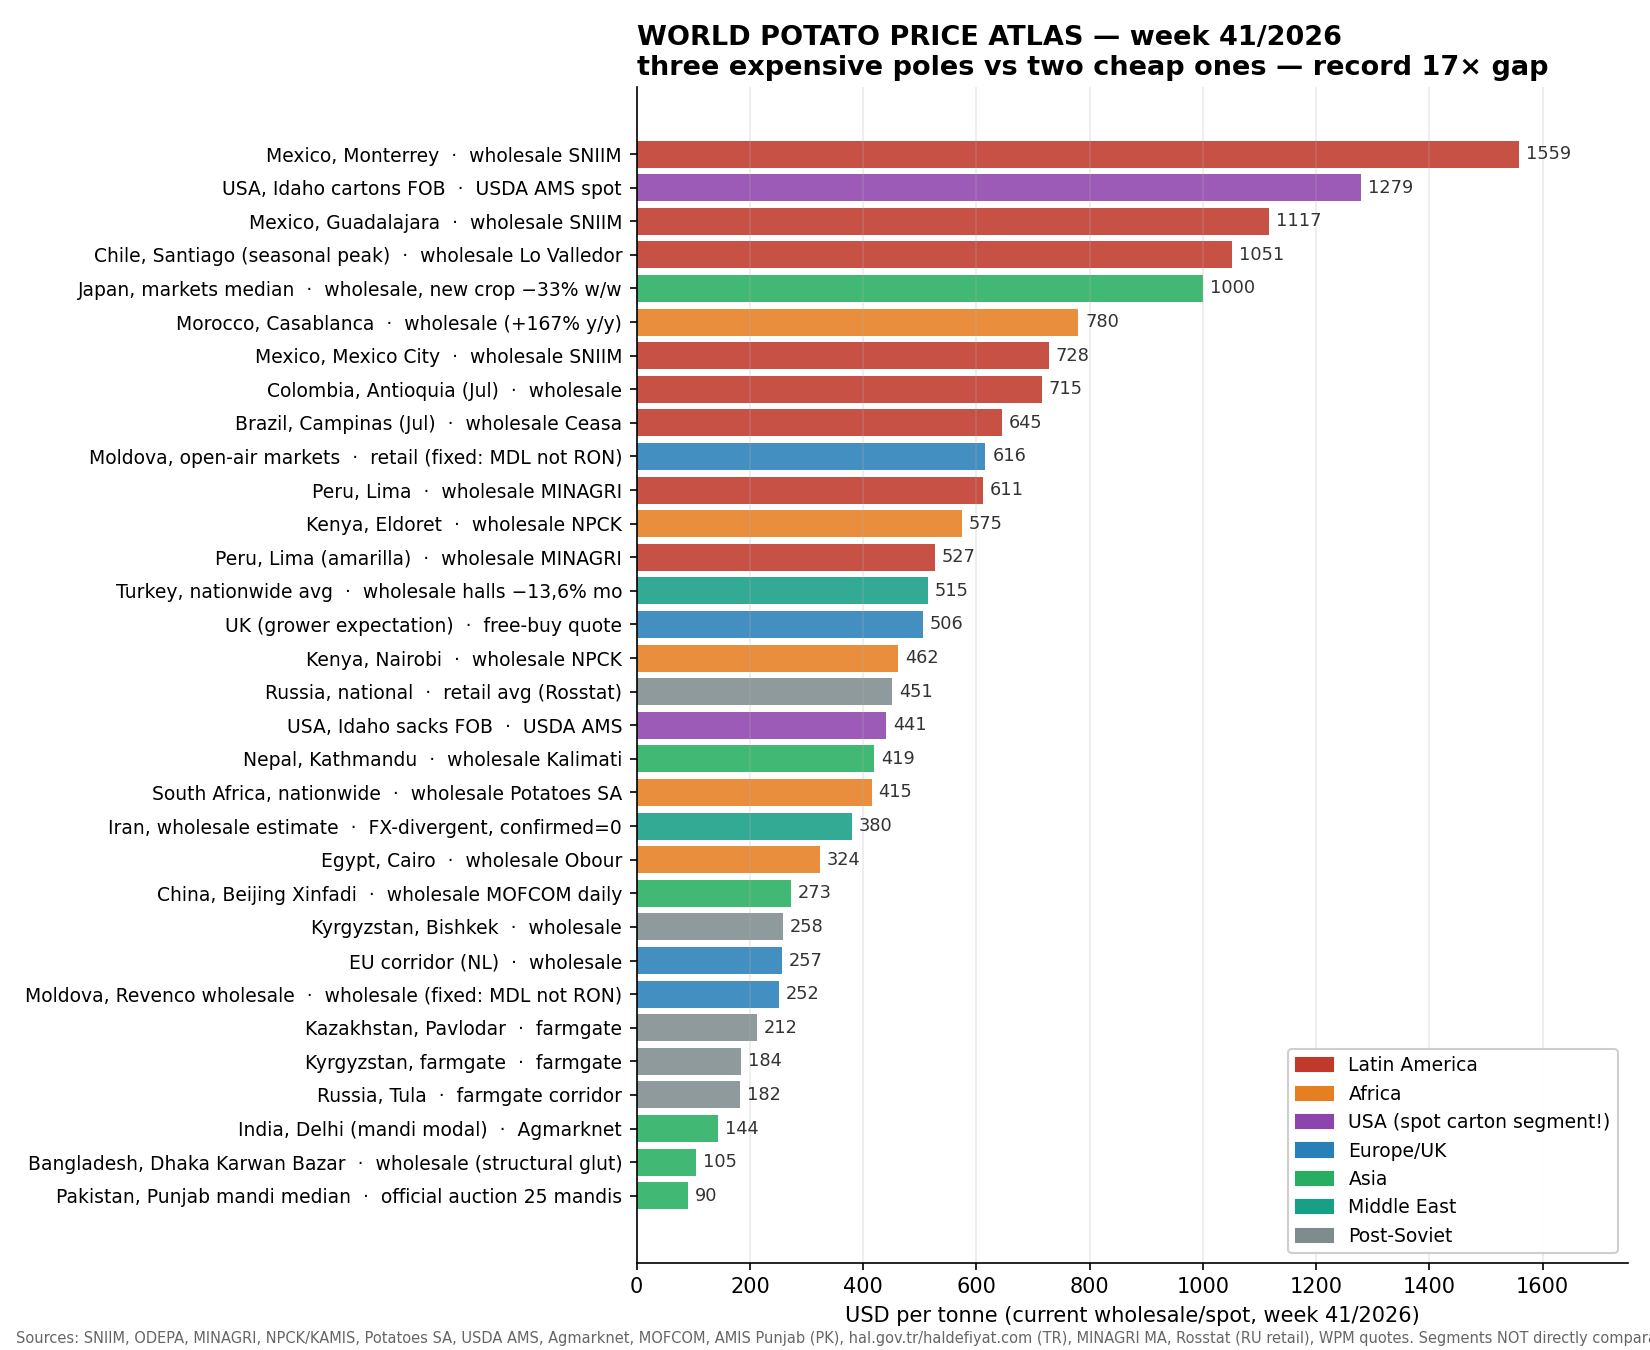
Weekly price bulletin: France at a record 1100 USD/t, Mexico in crisis at 1559, Pakistan the new world floor at 90 — the global potato market has never been this split.
Evening edition, 11 October 2026 · internal editorial document, potatoes.news
Basis: GLOBAL-DASHBOARD-W41 · price_obs + FAOSTAT + World Bank + USDA AMS + Agmarknet · FX: Bank of Russia rates of 10.10.2026
1. PRICE LEVELS AROUND THE WORLD (week 41)
| Market | Segment | Price | USD/t | Date | Status |
|---|---|---|---|---|---|
| USA, Idaho | Burbank, 50 lb cartons FOB | $28–30 | 1235–1323 | 10.10 | VERIFIED (USDA AMS) |
| USA, Idaho | Norkotah, sacks FOB | $20/cwt | ~441 | 11.10 | VERIFIED |
| United Kingdom | free-buy (grower expectation) | £360–400/t | 480–533 | 10.2026 | media, confirmed=0 |
| Nepal, Kathmandu | wholesale Kalimati, local | 54–57 NPR/kg | 408–430 | 11.10 | VERIFIED (market board) |
| Kyrgyzstan | wholesale Bishkek, sacks | 20–25 KGS/kg | 230–287 | 09.10 | VERIFIED (antimonopoly service) |
| Egypt, Cairo | wholesale Obour | 17 EGP/kg | 324 | 29.09 | VERIFIED (Cairo24) |
| Netherlands | wholesale corridor | €20–26/100kg | 224–290 | 10.2026 | upper end ONE SOURCE |
| Canada | annual 2025 (backdrop v3) | — | 304 | 2025 | ANNUAL |
| Poland | annual 2025 (backdrop v3) | — | 293 | 2025 | ANNUAL |
| Germany | annual 2025 (backdrop v3) | — | 263 | 2025 | ANNUAL |
| Kazakhstan | farmgate Pavlodar | 95 KZT/kg | 212 | 02.10 | VERIFIED (Kazinform) |
| Russia, national | retail average | 38.3 RUB/kg | ~451 | 11.10 | VERIFIED (Rosstat consumer price monitor) |
| Russia, Tula | farmgate corridor | 13–18 RUB/kg | 153–212 | 11.10 | VERIFIED (2 boards) |
| India, Delhi | mandi modal FAQ | 1220 INR/quintal | ~144 | 06.10 | VERIFIED (Agmarknet) |
| Bangladesh, Dhaka | wholesale Karwan Bazar | 11–12 BDT/kg | 100–110 | 08.2026 | VERIFIED (2 media + wholesaler quotes) — structural floor (surplus 11.5M t vs demand 9M t) |
| Turkey, nationwide | wholesale avg, 15–16 halls | 25.38 TRY/kg | 515 | 17.09 | VERIFIED (official hall quotes, −13.6% m/m) |
| Turkey, Antalya | hall wholesale (peak) | 37.5 TRY/kg | 761 | 16.09 | official quote, confirmed=1 |
| Turkey, Bolu | municipal list | 14–17 TRY/kg | 284–345 | 08.05 | official (Bolu Municipality) |
| Iran, wholesale (estimate) | wholesale/export | ~190k IRR/kg | ~380 | 10.2026 | FX-DIVERGENT (like Argentina): USD confirmed=0; official PPI 2025 +49.5% y/y |
| Pakistan, Punjab (median of 25 mandis) | official auction AMIS | 2550 Rs/100kg | ~90 | 11.10 | VERIFIED (official AMIS Punjab) — world floor, FX ~282 confirmed=0 |
| Pakistan, farmgate (Jan crisis) | farmgate in glut | 10–15 Rs/kg | ~35–53 | 01.2026 | VERIFIED (Dawn A): demand 6.2M t vs crop ~12M t |
| Japan, markets median | wholesale (new crop, −33% w/w) | 158 JPY/kg | ~1000 | 10.10 | VERIFIED (agrine.jp; FX 157.35) — Asia’s expensive pole |
| Japan, Yokohama range | wholesale by origin | 173–302 JPY/kg | 1100–1716 | 10.10 | VERIFIED (青果市況 sheet) |
| China, median of 112 markets | wholesale MOFCOM daily | 2.3 CNY/kg | 322 | 10.10 | VERIFIED (S) |
| China, Beijing Xinfadi | wholesale MOFCOM | 1.95 CNY/kg | 273 | 10.10 | VERIFIED (S) |
| Kyrgyzstan | farmgate | 15–17 KGS/kg | 172–195 | 08.10 | VERIFIED |
| Kenya, Nairobi | wholesale (NPCK) | 56–64 KES/kg | 430–495 | 09.10 | VERIFIED |
| Kenya, Eldoret | wholesale (NPCK) | 74 KES/kg | ~575 | 09.10 | VERIFIED |
| South Africa, nationwide | wholesale FPM, 10kg bags | R7.0–7.7/kg | 395–435 | 08.10 | VERIFIED (Potatoes SA) |
| Mexico, Mexico City | wholesale SNIIM, Alpha | 14.00 MXN/kg | 728 | 09.10 | official via aggregator, confirmed=0 |
| Mexico, Monterrey | wholesale SNIIM, Alpha | 30.00 MXN/kg | 1559 | 09.10 | official via aggregator, confirmed=0 |
| Chile, Santiago | wholesale Lo Valledor (ODEPA), seasonal peak | 25,000 CLP/25kg | 1051 | 09.10 | official via aggregator, confirmed=0 |
| Peru, Lima | wholesale MINAGRI, Canchan | S/2.18/kg | 611 | 08.10 | VERIFIED (SISAP bulletin) |
| Brazil, Campinas | wholesale Ceasa (July checkpoint) | 3.20–4.00 BRL/kg | 573–716 | 30.07 | ONE SOURCE (ArgenPAPA) |
| Colombia, Antioquia | wholesale (July checkpoint) | 2900 COP/kg | 715 | 30.07 | ONE SOURCE (ArgenPAPA) |
| Morocco, Casablanca | wholesale (cold-store stocks) | 7–8 MAD/kg | 730–830 | 05.10 | VERIFIED (2 media + wholesaler quote), +167% y/y |
| Morocco, annual 2024 (real) | FAO backdrop | — | 388 (+22%) | 2024 | VERIFIED (A); 2025 ≈480 PROVISIONAL |
| Nigeria, Lagos | wholesale Mile 12 | n/a | — | 10.2026 | WHITE SPOT: FAO breaks off 2013; route: NBS |
Segments are kept apart: carton FOB, sack FOB, wholesale, free-buy, mandi and annual backdrop are not comparable (methodology rule §1).
2. MOVEMENTS (verified pairs)
| Market | Change | Period | Reliability |
|---|---|---|---|
| France, annual (real) | +17.6% (936→1100 USD/t) | 2024→2025 | VERIFIED (v4), world record |
| Germany, annual (real) | +13.5% (342→388 USD/t) | 2024→2025 | VERIFIED (v4) |
| Russia, annual (real) | +11.6% (210→234 USD/t) | 2024→2025 | VERIFIED (v4) |
| USA, annual (real) | +6.4% (267→284 USD/t) | 2024→2025 | VERIFIED (v4, double cross-check) |
| United Kingdom, annual (real) | −23.2% (529→406 USD/t) | 2024→2025 | VERIFIED (v4), retreat from peak |
| India, Azadpur mandi | +43.5% (850→1220 INR/q) | 04.07→06.10 | VERIFIED, seasonality |
| Kazakhstan, farmgate | −5.0% (223→212 USD/t) | 24.09→02.10 | VERIFIED (Kazinform) |
| Poland, annual (real) | 0.5% (218→219 USD/t) | 2024→2025 | VERIFIED (v4) |
| Market | Change | Period | Reliability |
|---|---|---|---|
| India, Azadpur mandi | +43.5% (850→1220 INR/q) | 04.07→06.10 | VERIFIED, seasonal rise off harvest floor |
| Poland, annual (real) | +34.3% (218→293 USD/t) | 2024→2025 | VERIFIED (v3) |
| Belarus, annual (real) | +43.7% (107→154 USD/t) | 2024→2025 | VERIFIED (v3) |
| Russia, annual (real) | +11.6% (175→195 USD/t) | 2024→2025 | VERIFIED (v3) |
| Germany, annual (real) | −23.0% (342→263 USD/t) | 2024→2025 | VERIFIED (v3) |
| USA, annual (real) | −12.4% (267→234 USD/t) | 2024→2025 | VERIFIED (v3, double cross-check) |
| Kazakhstan, farmgate | −5.0% (223→212 USD/t) | 24.09→02.10 | VERIFIED (Kazinform) |
| France, annual (real) | −25.3% (936→699 USD/t) | 2024→2025 | VERIFIED (v3), retreat from all-time peak |
3. ANALYST’S COMMENT
- France sets a new world record: 1100 USD/t (real 2024) in 2025, a third consecutive year of growth (880→936→1100). The European deficit is not exhausted; Germany +13%, USA +6%, Russia +12% — moderate growth almost everywhere; only the UK retreats (−23% off its 2024 peak). The global split hit an all-time high: France is 8× Ukraine — the maximum of the entire 1991–2025 series.
⚠ v4 correction: an earlier version of this bulletin carried a false "reversal of the year" (Poland +34%, Belarus +44%) — an artefact of monthly rows in FAOSTAT data. Recomputed on clean annual values in the W41 dashboard. - The USA is two markets in one country: fresh cartons FOB $1235–1323/t versus an annual producer price of $258/t. A thin spot market plus contracted processing means every US figure must carry its basis, or the false conclusion "America is the most expensive" follows.
- India is rising off the floor: mandi modal at 1220 INR/quintal (+43.5% since July), but this is seasonality, not trend. Spring saw 260–280 USD/t — India’s volatility remains the world’s largest (a 9.5× spread inside a single mandi).
- Africa is an expensive pole that nobody mentions: Kenya at 430–575 USD/t wholesale (official NPCK/KAMIS) — on par with the UK; South Africa +70% in a season (255→415) amid extreme vegetable inflation (onions +268% y/y). Cheap Asia and expensive Africa coexist — a gap of up to 4× within Africa/Asia.
- Latin America is the third expensive pole — and Mexico is in crisis: annual 2024 — Colombia 555 (+30%), Brazil 534 (+34%), Mexico 521; current October wholesale — Mexico 728–1559 USD/t (Mexico City retail +101.5% y/y, Profeco), Chile 1051 (seasonal peak at Lo Valledor), Peru 527–611 (MINAGRI). Mexico is currently more expensive than France. Argentina is excluded from USD comparisons — currency controls break the conversion (methodology rule).
- Morocco — a second African price crisis: Casablanca wholesale 730–830 USD/t, +167% y/y (7–8 MAD/kg vs ~3 a year ago) on cold-store stocks after a weak, drought-hit harvest — a ~4× jump from the January farmgate floor of 2 MAD. Nigeria remains a documented white spot (FAO absolute prices break off in 2013; NGN official/parallel FX gap persists) — closure route: NBS food price watch.
- Turkey — the first regular Middle East contour is open: nationwide wholesale average 515 USD/t (25.38 TRY/kg across 15–16 official wholesale halls, hal.gov.tr via haldefiyat.com), −13.6% month-on-month — the autumn seasonal floor; quality spread runs 8–50 TRY/kg = 162–1015 USD/t. The Bolu corridor of 14–17 TRY/kg has held since February — a benchmark for cross-border trade.
- Iran — the second FX-divergent country after Argentina: the official IRR/USD rate understates the price several-fold over, so no USD series is built (methodology rule). Official potato PPI: +49.5% y/y in 2025 (FAOSTAT); Tehran retail passed 500,000 IRR/kg in February 2025 (×3.3 in a year, Iran International) — amid 105–134% food inflation potatoes were the "slowest" food item (~+20% y/y, May 2026). Wholesale estimate ~380 USD/t carries confirmed=0.
- Pakistan — the new world floor (90 USD/t) and Asia’s second glut crisis: official auction wholesale AMIS Punjab (41 mandis, daily): median 25.5 Rs/kg ≈ 90 USD/t on 11.10 — below Bangladesh. January crisis: farmgate 10–15 Rs/kg below cost, demand 6.2M t vs a ~12M t crop, Afghan border closed (Dawn; government answer — export mobilisation to 36 countries, MNFSR); +72% rebound by August (PBS). Free daily source — joins the weekly collection.
- Japan — Asia’s expensive pole (1000 USD/t): wholesale median 158 JPY/kg even after a −33% w/w drop as the new crop arrives; backdrop — a small Hokkaido harvest (MAFF: >+30% vs the 5-year average) and Japanese food inflation. Asia is the world’s most split region: Pakistan 90 / Japan 1000 = 11× inside one continent.
- UK is chasing its 2024 peak: free-buy recovering toward £360–400/t after February’s slump (£180). No official report exists (AHDB closed in 2022) — the figure is a media quote, pending confirmation.
4. CAVEATS
- All conversions at Bank of Russia (CBR) rates of 10.10.2026; for non-ruble markets this is a comparability convention.
- Subscription sources (WPM, IKAR): signal only; open duplication required before on-site publication.
- EEX futures (Trading Economics) excluded from benchmarks (broken CFD, 15–20× below reality).
- Annual changes 2024→2025 in real USD-2024, v4 (clean annual data); India 2025 reconstructed via FAO index.
- Latin America: current-price USD conversions use WB-2025 annual average rates (PEN 3.57; CLP 951; MXN 19.24; BRL 5.59; COP 4053) — estimates, confirmed=0; local-currency prices from official bulletins. FAO 2025 (flag E) excluded: internally inconsistent by 1.5–3×.
5. KEY TAKEAWAY
Week 41/2026: the potato world is split into three expensive poles — Europe (France at a record 1100), Africa (Kenya 430–575) and Latin America (Mexico now 728–1559, in crisis at +101.5% y/y) — against cheap Asia (India 144) and the post-Soviet space (Russia 234, Ukraine 139), a record gap of up to 8×. A "potato price" without a basis and a segment is not a price: the US proves it weekly (FOB cartons 1235–1323 vs an annual 258). Watch: a second source for UK free-buy £400 and for the Mexican crisis; in October the Western Hemisphere is more expensive than the Eastern — a first for the entire observation series.
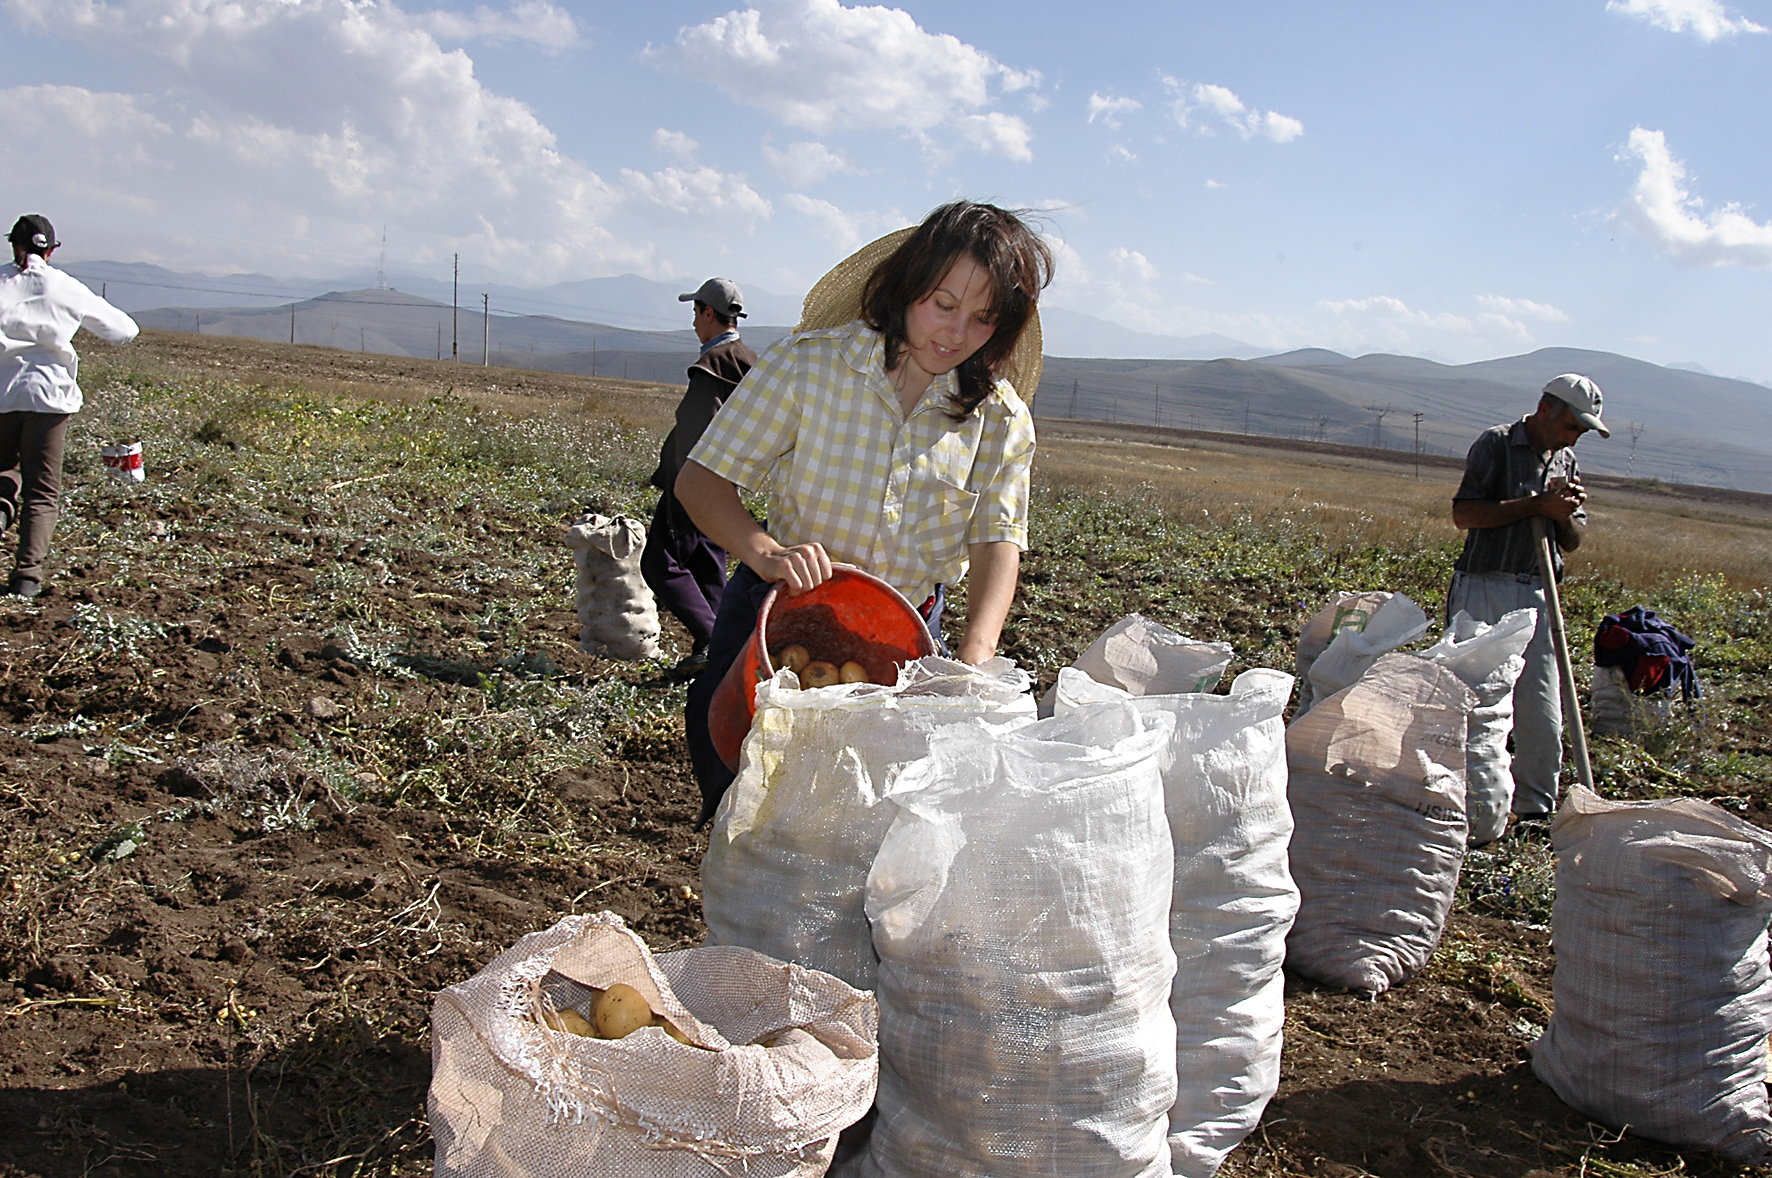
Photo: Narek75 / Wikimedia Commons, CC BY-SA 4.0