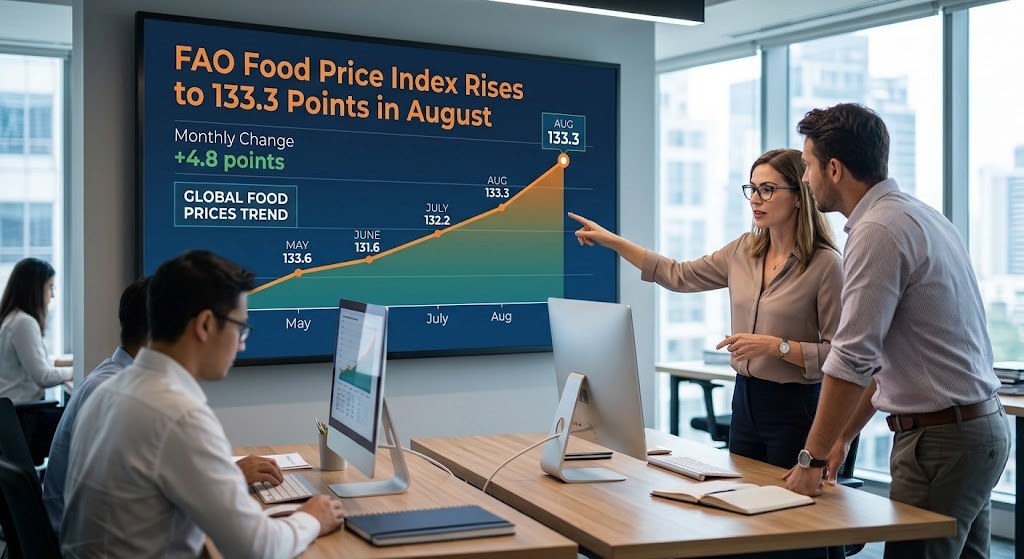
The FAO Food Price Index averaged 133.3 points in August 2026, against a revised July reading of 130.8 — up 1.9 percent month-on-month and 2.5 percent year-on-year. All five commodity groups gained: sugar 11.9 percent (highest since June 2025), dairy 2.3 percent, cereals 2.2 percent, vegetable oils 1.1 percent, meat 1.0 percent. The index nonetheless remains 16.8 percent below its March 2022 peak.
World cereal production in 2026 is forecast at 2,980 million tonnes, 2.0 percent below 2025 but still the second-largest harvest on record. The maize forecast has been cut to 1,309 million tonnes, as deteriorating crop prospects in France and Poland outweigh better-than-expected yields in Argentina and Brazil. The wheat forecast has been raised to 810.7 million tonnes, 3.8 percent below 2025.
FAO Chief Economist Maximo Torero attributed the increase to a risk premium returning to food markets, with climate shocks, geopolitical tensions and disrupted trade logistics converging to tighten supply expectations. FAO
Weekdays. Unsubscribe in one click.
Relevance to the potato sector
Potatoes are not in the FAO basket, which covers cereals, vegetable oils, dairy, meat and sugar. But three of August’s drivers sit on the same ground and the same weather window as the European potato crop.
FAO attributes its European downgrades to hot, dry conditions — the same episode that shaped the North-West European potato season. The maize revision is specifically French and Polish.
Lower expected EU sugar beet yields matter directly for rotation planning: beet competes with potatoes for area, and a weak beet season changes the 2027 planting calculation.
FAO also cites input disruption linked to the closure of the Strait of Hormuz. That reaches nitrogen fertiliser and energy, and therefore storage and planting costs for the 2027 crop.
Practical read: firmer cereal and dairy prices strengthen the case for competing rotation crops, while higher input costs lift the floor under potato production costs going into spring. In autumn contract talks with processors, general food inflation works in the grower’s favour — but only where cost increases are documented.