Idaho braces for smallest potato crop since 2011 as prices climb to three-year high
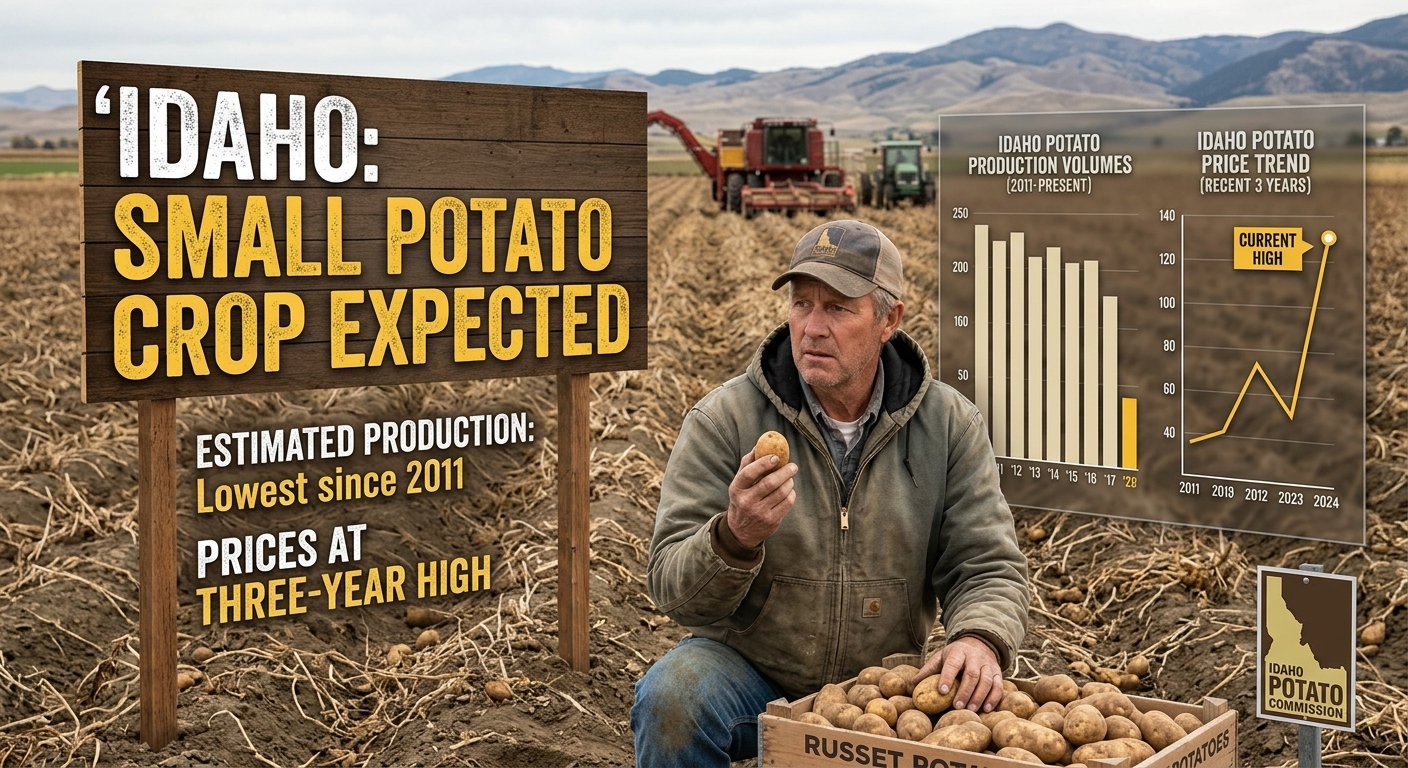
Back-to-back May frosts and a hot summer have cut yields in America’s largest potato-producing state, on top of a planted area already reduced after a disastrous 2025 price season. With harvest now under way, Idaho potatoes are fetching their highest prices since summer 2023, and growers expect the tightest supply to come next spring.
A season hit twice
Industry participants quoted by FreshPlaza on 10 September expect Idaho’s 2026/27 potato crop to be the smallest since 2011. This is a trade expectation rather than an official figure: USDA’s National Agricultural Statistics Service (NASS) has not yet published a production estimate for the state.
Ryan Wahlen of Pleasant Valley Potato traced the shortfall to two separate weather events. In early May, just as plants were emerging, temperatures dropped to −5°C (23°F). A second frost two weeks later caught the plants that had not yet emerged the first time round.
Weekdays. Unsubscribe in one click.
The second blow came in July and August, when significant heat struck during tuber bulking. Wahlen said water curtailment made it difficult to keep the crop cool. Growers delayed the start of harvest by a week in the hope of adding size; with lower yields, lifting is now moving faster than usual and is expected to run to the end of September.
Quality, by contrast, is good. Tubers are smaller but smooth, with fewer of the growth cracks and misshapen potatoes typically associated with rapid growth, Wahlen said.
Two acreage figures, two methodologies
Reports on Idaho’s planted area cite different numbers. They come from different sources and are not directly comparable:
- USDA/NASS (Acreage report, 30 June): 121,406 ha (300,000 acres), down 5% from 127,476 ha (315,000 acres) in 2025. The cut of 6,070 ha (15,000 acres) is the largest of any state.
- Idaho Potato Commission (own physical field count): 120,967 ha (298,915 acres). The Commission’s equivalent count for 2025 was 126,685 ha (313,045 acres), implying a decline of about 4.5% on a like-for-like basis.
Some coverage compares the Commission’s 2026 count with USDA’s 2025 estimate, arriving at a 5.1% fall. Because the two series use different methods, that comparison overstates the change.
Wahlen described the area as the fourth-smallest planted in Idaho in 70 years and attributed the cut primarily to price. In his view, 2025 was the worst year on record for potato prices. In April, North American Potato Market News (NAPMN) reported that Idaho open-market potatoes were selling for under USD 2 per hundredweight (roughly USD 4.41 per 100 kg), far below the cost of production.
National area at a 74-year low
USDA puts total US potato plantings for 2026 at 353,291 ha (873,000 acres), down 11,736 ha (29,000 acres), or 3%, on 2025. It is the third consecutive annual decline, after 390,926 ha in 2023, 377,167 ha in 2024 and 365,026 ha in 2025, and the smallest US area since 1952.
Eight states reduced plantings and none increased them. Idaho accounted for around half of the national reduction. Washington, the second-largest producer and the heart of the US processing sector, held its area unchanged.
The acreage low does not translate automatically into a comparable production low, as yields today are far higher than in the 1950s. In July, NAPMN forecast that total US output could fall by only 2% on the back of higher average yields. That forecast pre-dates the summer heat and does not reflect the losses now emerging in Idaho, and an updated national estimate is yet to be published.
Prices: the squeeze is expected in spring
Demand for Idaho potatoes currently exceeds supply and may continue to do so until harvest is further advanced, according to Wahlen. He expects prices to stay higher than anticipated throughout the season. Carton prices may ease slightly before the end of the year, but the crop is short and smaller in size profile than buyers are used to.
The real pressure is expected in spring and summer 2027, when storage potatoes normally cover late-season orders. With that segment potentially very tight, growers anticipate prices holding firm or strengthening rather than falling.
Europe faces its own shortfall
Idaho’s problems coincide with a much steeper contraction across the Atlantic. In its first estimate, presented on 14 September, the North-Western European Potato Growers (NEPG) put ware potato production in Belgium, France, Germany and the Netherlands at about 20.7 million tonnes, 25.4% below 2025. Ware area in the four countries fell 13.7% to 521,455 ha, and Belgium faces the sharpest drop in output, estimated at 35.3%.
There is virtually no direct trade in fresh potatoes between the US and Europe, so Idaho’s crop will not move European ware prices directly. The link runs through processed products: North America and Europe are the dominant exporters of frozen potato products and compete head to head in Asia, the Middle East and Latin America. In that context, a simultaneous tightening of raw material supply in both regions could lend support to global frozen fry prices and ease competitive pressure on European processors, although the US processing base in Washington has so far been less affected than Idaho.
Sources
- FreshPlaza, “Fewer acres and lower yields for Idaho potatoes in 2026”, 10 September 2026: https://www.freshplaza.com/north-america/article/9871582/fewer-acres-and-lower-yields-for-idaho-potatoes-in-2026/
- Idaho Farm Bureau, “Idaho potato acres drop by 5%”, 8 July 2026: https://www.idahofb.org/news-room/posts/idaho-potato-acres-drop-by-5/
- Idaho Farm Bureau, “Idaho potato acres forecast to decline 5 percent”, 16 April 2026: https://www.idahofb.org/news-room/posts/idaho-potato-acres-forecast-to-decline-5-percent/
- Idaho Farm Bureau, “A look at Idaho crop acres in 2025”, 1 July 2025: https://www.idahofb.org/news-room/posts/a-look-at-idaho-crop-acres-in-2025/
- AgWest Farm Credit, Potatoes – industry insights, 12 August 2026: https://www.agwestfc.com/education-and-resources/industry-and-economic-insights/industry-insights/potatoes
- FreshPlaza (Spain), “La NEPG estima una cosecha de patata un 25,4% menor en 2026”, 15 September 2026: https://www.freshplaza.es/spain/article/9873194/la-nepg-estima-una-cosecha-de-patata-un-25-4-menor-en-2026/
Global Potato Brief
Top five stories, prices, disease alerts and events. Weekday mornings, no advertising.
Linked in this material
- Sections
- News
Related stories
Students of the Institute of Agrobiotechnology Harvest Over 23 Tonnes of Potatoes
China Potato Congress 2026: Official Agenda Stays Domestic as Equipment Makers Pitch a Global Story